
What does a spending target actually buy on a map? In June 2025, NATO allies meeting in The Hague committed to a goal of 5 percent of GDP on defense and security by 2035, with 3.5 percent earmarked for core military capability and the rest for related areas such as infrastructure and cyber defense. The figure grabbed headlines, but the planners who work on the alliance’s eastern frontier are asking a more practical question: where does each additional euro land, and how fast?
The answer is changing the logic of eastern flank planning. For years the region was defended by modest forces meant to signal commitment. Now the money is large enough to support a different model, one built on denying an attacker progress rather than promising to liberate territory after it falls. That shift touches everything from where depots are built to which rail gauges matter.
From Tripwire to Defense in Depth
The original concept behind NATO’s forward presence in the Baltic states and Poland was the tripwire. Multinational battlegroups, small by military standards, were deployed after 2014 so that any incursion would immediately involve soldiers from several allied nations. The idea was political as much as military: an attack on them would be an attack on everyone, and Moscow would know it. The 2022 invasion of Ukraine pushed the alliance to extend the battlegroup model to four more countries along the flank, including Romania, Bulgaria, Hungary and Slovakia.
A tripwire works only if nobody tests it, and larger budgets let planners move past it. The emerging approach layers air defense, long-range fires, prepared obstacles and pre-positioned equipment so that a first strike meets resistance at every stage. Denial is more expensive than symbolism, and it demands that front-line states and their larger partners agree on who holds what, years in advance.
Where the Money Is Going
Air and missile defense sits at the top of most shopping lists. Drones and missiles crossing into Polish airspace during the war in Ukraine showed how thin the layers could be, and the response included the Eastern Sentry operation, which pulled allied aircraft and sensors into a more coordinated posture along the border. Interceptors are costly, and using a multimillion-euro missile against a cheap drone is an exchange ratio no finance ministry enjoys. That is why a growing share of procurement debates now concerns cheaper counter-drone systems, guns and electronic warfare rather than only high-end batteries.
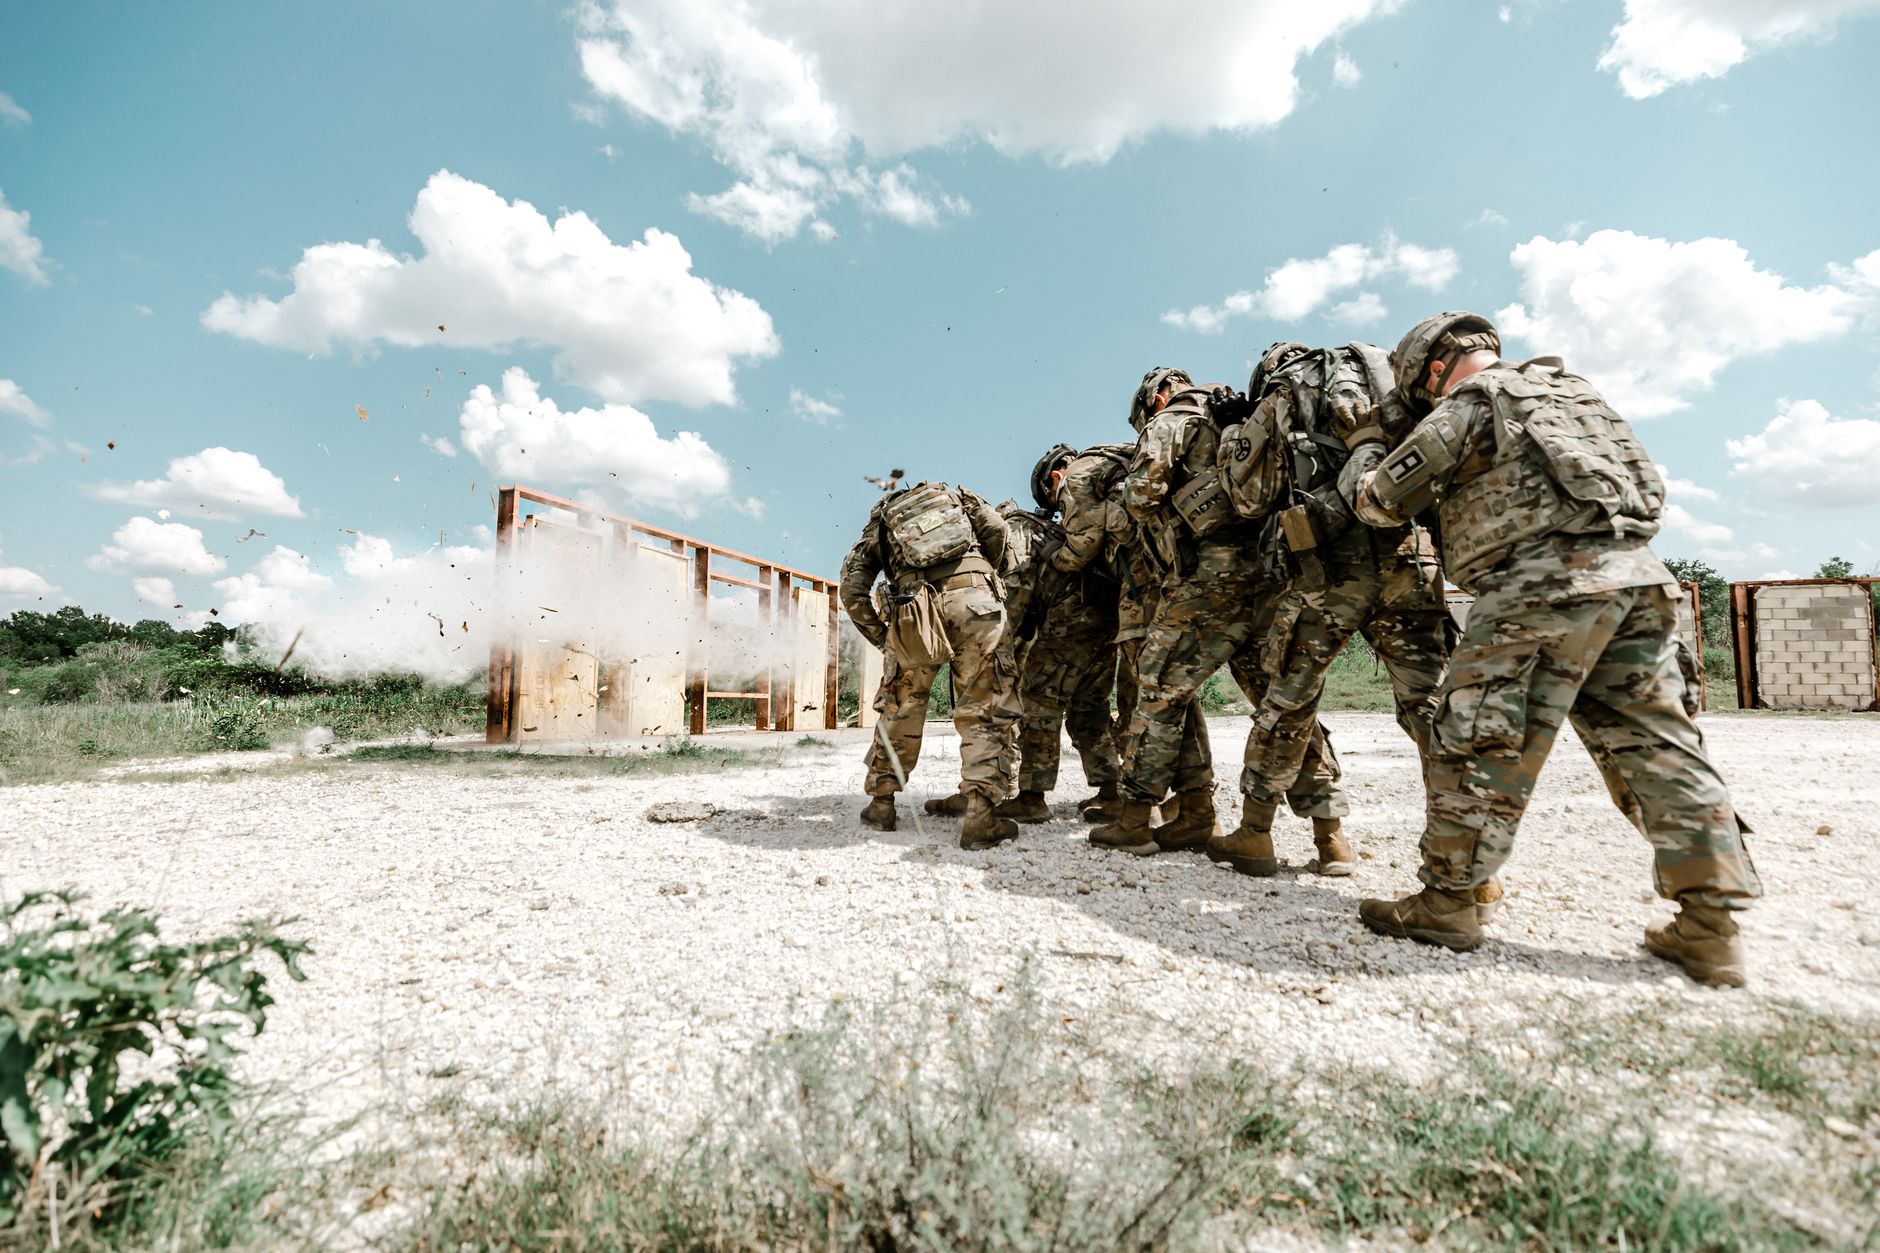
Ground forces are the second big line. Poland now spends close to or above 4 percent of GDP, the highest share among the alliance’s larger members, and has pursued a fortification program along its borders with Belarus and Russia’s Kaliningrad exclave. The Baltic states have been building their own defensive lines, including anti-vehicle obstacles and bunker networks. These are unglamorous projects, yet they change an adversary’s arithmetic, because a prepared defender can hold ground with far fewer troops than an improvised one.
Germany is the biggest swing factor. Berlin loosened its constitutional debt brake so that most defense spending above a threshold of 1 percent of GDP no longer counts against borrowing limits, removing a restriction that had constrained the largest European economy for years. It has also committed to stationing a combat brigade permanently in Lithuania, a significant departure from the long-standing German habit of rotating forces rather than basing them abroad. A permanent brigade needs housing, schools, training grounds and supply chains, so the commitment is as much construction project as military one.
Then there is mobility, the least visible category and arguably the most demanding. Moving heavy armor across Europe means bridges that bear the weight, rail lines that connect, and customs and permit rules that do not slow a convoy at every border. The Baltic states still run into the legacy of a different rail gauge from much of Western Europe, which complicates reinforcement. Money spent here rarely makes the evening news, but a division that cannot arrive in time is a division that does not count.
The Industrial Bottleneck
Budgets can grow faster than factories. European defense producers spent decades fulfilling small, irregular orders, and many production lines were built for peacetime rhythms. Artillery shells, air defense interceptors and armored vehicles all require supply chains for propellants, electronics and specialty steel that cannot be expanded by decree. Governments are now signing multiyear contracts partly to give manufacturers the confidence to build new capacity, but a new plant takes years to open, and meanwhile the orders pile up.
Fragmentation makes the problem harder. Europe fields a wider variety of tank types, howitzers and fighter jets than the United States does, which complicates maintenance, training and ammunition supply. Joint procurement programs are meant to narrow that field, though national industrial interests keep pulling in the other direction. A Polish decision to buy South Korean tanks and artillery, made partly because of delivery speed, shows how urgency can override the preference for keeping contracts within the European family.
Who Carries the Burden
The spending surge arrives alongside doubts about American attention. Washington has signaled that it expects Europe to take the lead on conventional defense on its own continent, while the United States focuses more on the Indo-Pacific. That puts pressure on European planners to fill specific gaps that America has long covered, such as intelligence, surveillance, aerial refueling, and the command systems that tie everything together. Money alone cannot buy these quickly, and some may take most of a decade to develop.
Inside the alliance, the geography of risk produces uneven enthusiasm. Countries bordering Russia and Belarus treat the 5 percent goal as a floor, while allies farther west and south face competing demands from aging populations, debt and other security concerns such as Mediterranean migration and instability. The target is a political compromise, and its credibility depends on whether governments with tight budgets keep funding it through elections and downturns.
The sharpest tension is one that no spending figure resolves. A tank ordered today may not roll off a line until the early 2030s, while the window of greatest concern for eastern flank planners is widely discussed as the next few years. If the capabilities arrive after the moment they were meant for, the alliance will have bought a very strong defense for a threat that has already moved on.
Frequently Asked Questions
What spending target did NATO allies agree to in 2025?
At the Hague summit, allies committed to spending 5 percent of GDP on defense and security by 2035, including 3.5 percent on core military capability and 1.5 percent on related areas such as infrastructure and cyber defense.
What is NATO’s eastern flank?
It is the band of allied countries bordering or near Russia and Belarus, from the Baltic states and Poland down to Romania and Bulgaria, where NATO maintains multinational battlegroups.
Why does defense industry capacity matter for the spending increase?
Larger budgets only translate into capability if factories can produce munitions, vehicles and air defense systems at scale, and many European production lines were built for small peacetime orders.